Explore plan options

Shop Iowa plans
Health plans for small businesses in Iowa
Shop South Dakota plans
Health plans for small businesses in South Dakota
Shop vision plans
Make sure your health coverage includes vision benefits

Shop dental plans
Add dental benefits to your plan—only available in Iowa
Finding the right plan starts here
Whether you have one employee or 50, Wellmark gives you clear plans, the largest provider network, reliable member support and some of the best benefit options—all designed to fit your budget.
Take a closer look. Our plan comparison guide offers step-by-step guidance to find a plan that’s right for you and your employees.

About Wellmark
Why choose Wellmark
Learn more about Wellmark—affordability, access and our exceptional member support.
FAQs about small business health plans
To be eligible to purchase and maintain group health insurance, a group account must meet specific criteria established by applicable law and Wellmark. This includes, but is not limited to:
- Your business must be headquartered in Iowa or South Dakota as confirmed on the Secretary of State’s website. (Note: Sole proprietors, public entities and some types of partnerships do not appear on the Secretary of State’s website.)
- The account must be an entity that has the legal capacity to execute a contract on behalf of its employees.
- The account must be formed for reasons other than obtaining health coverage.
- An employer/employee relationship should exist, meaning eligible individuals comprising the account are bound together for reasons of financial gain. This includes for-profit corporations, professional corporations, non-profit corporations, limited liability companies, limited partnerships, limited liability partnerships, partnerships and sole proprietorships.
- The account must have at least one full-time, common-law employee (other than the sole proprietor owner/spouse or non-bona-fide partner/spouse) enrolling in coverage. Note: If a business is a sole proprietor, neither sole proprietor nor spouse are considered common-law employees even with a W-2.
- The account must be able to perform minimal administrative functions, such as paying premiums and maintaining group enrollment.
- Wellmark requires the group’s average number of employees to be employed on business days in the preceding calendar year.
Yes. If you’re purchasing coverage for at least one full-time, common-law employee, then the account qualifies as a group of one.
If you’re the owner and a common-law employee, then you’re eligible for small group coverage as a group of one. Note: If a business is a sole proprietor, neither sole proprietor nor spouse are considered common-law employees even with a W-2.
Get started by downloading one of our plan comparison guides. You’ll learn more about our small business health plans, broad provider network, member support and the extra benefits available with each plan.
Wellmark has comprehensive health insurance plan options for you and your employees. Plans are organized by network and metallic tier to help you choose what’s best for your business.
Disclosure
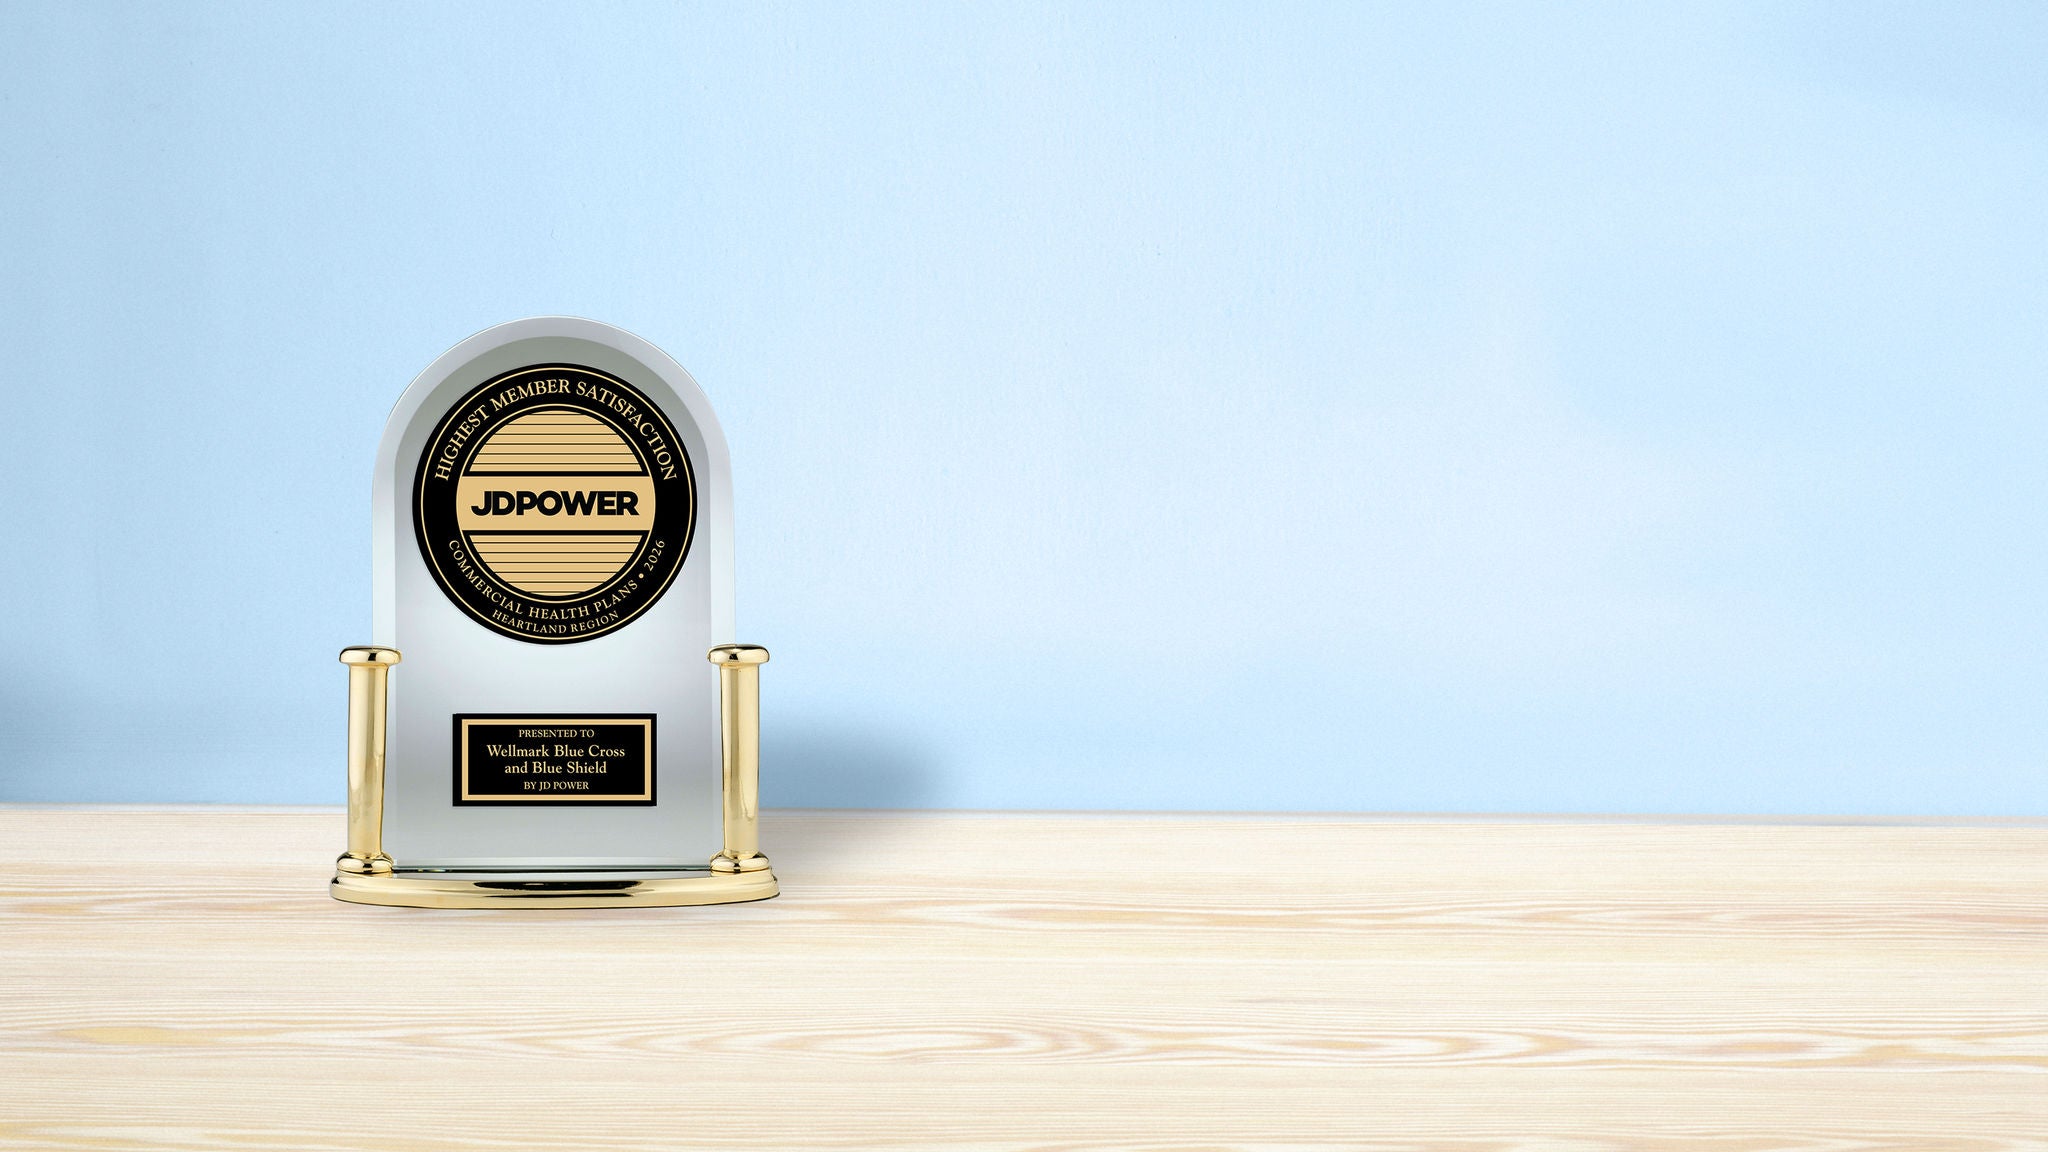
1Wellmark Blue Cross and Blue Shield received the highest score in a tie in the Heartland Region in the JD Power 2026 U.S. Commercial Member Health Plan Satisfaction Study, which measures members’ satisfaction with their commercial health plan experience. Visit jdpower.com/awards for more details.