Medicare and working past 65
As far as retirement age goes, there is no “normal.” It’s true, Americans, on average, retire at age 62. But that doesn’t mean they’re saying goodbye forever. Around 20 percent of retirees are choosing to re-enter the workforce and opt for part-time work or pursue a second career. Others continue working uninterrupted well past 65 years old. By 2030, it’s estimated the labor force of individuals 75 and older will grow by 96 percent.
If you’re 65 or older and employed, you're most likely wondering, “can I have Medicare if I'm still working?” It’s important to know how Medicare works, particularly if you or your spouse are enrolled in a health plan through an employer. Medicare eligibility begins at age 65, and signing up on time can help you avoid late enrollment penalties. But if you’re still working at 65 years old, you have a bit more flexibility.
If you are employed, but do not have health coverage from your current employer, a former employer or your spouse’s employer, you should enroll in Medicare Parts A and B during your Initial Enrollment Period. But if you have health coverage from your employer or through your spouse’s employer, you may not have to enroll in Medicare immediately.
6 things to know about Medicare if you're still working at 65
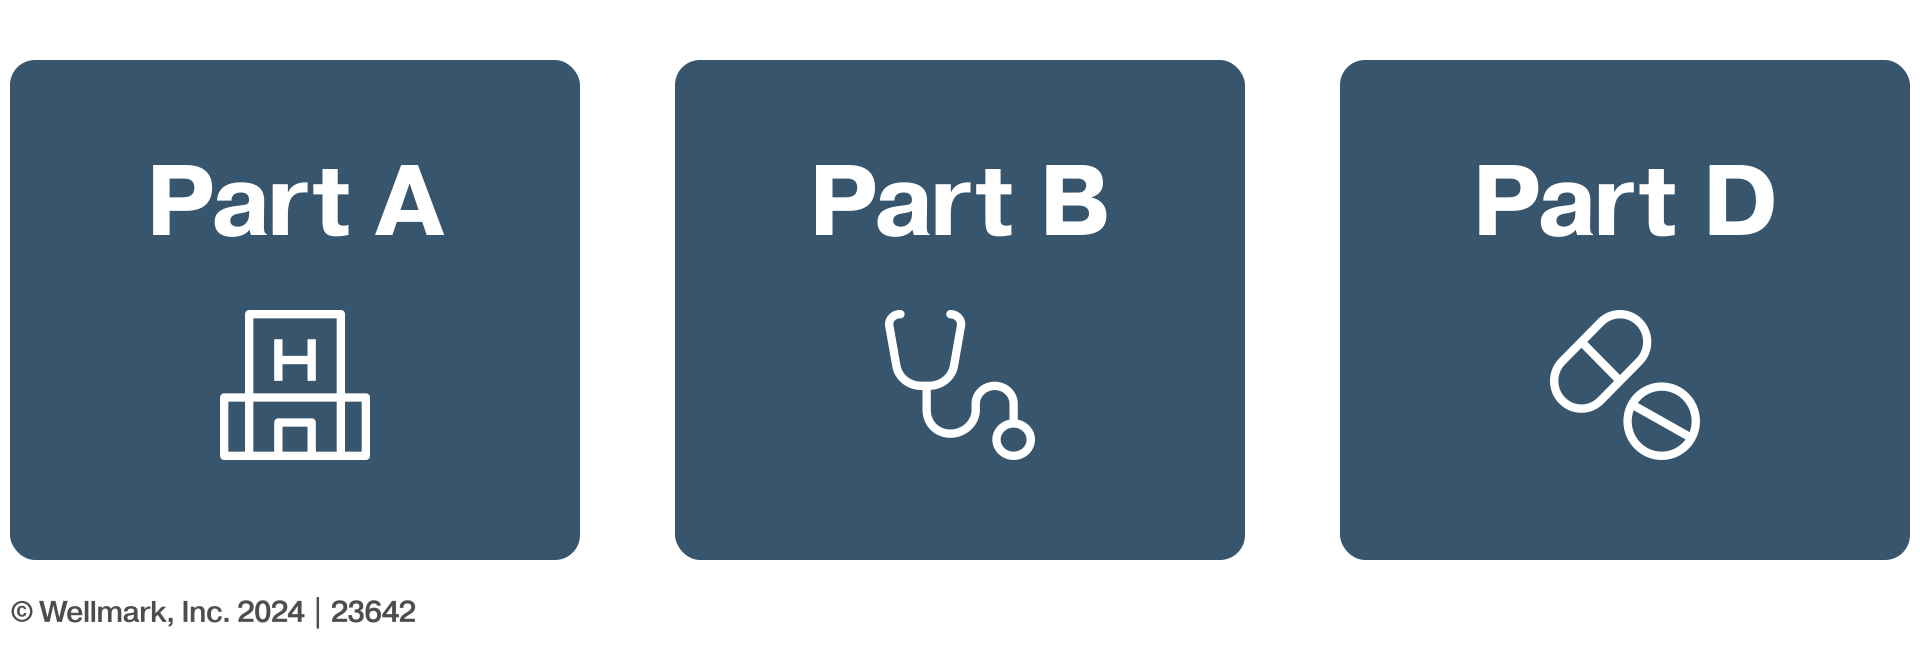
Infographic showing the three main parts of Medicare: Part A (hospital coverage), Part B (medical coverage), and Part D (prescription drug coverage), represented by hospital, stethoscope, and medication icons.
1.
In most cases, it’s a good idea to sign up for Part A
Medicare Part A provides coverage for in-patient hospital stays, skilled nursing facility care, hospice care and some home care. Most people benefit by enrolling in Medicare Part A at age 65, regardless of whether they continue to work. Generally, Medicare Part A can serve as your secondary insurance and potentially pick up the tab for anything your employer coverage doesn’t pay, so enrolling in Medicare when you turn 65 can help you avoid gaps in coverage later.
If you’re receiving Social Security benefits, you are automatically enrolled in Medicare Part A at 65 years old. If you’re not receiving benefits, you would need to sign up for Part A during your Initial Enrollment Period. This is a seven-month window that includes the three months before you turn 65, your birthday month, and the three months following your birthday.
Get more answers with our free guide
If you’re new to Medicare or just starting to consider your options, you can request our free Medicare Supplement Coverage Guide to learn the basics of Medicare, when you’re eligible to enroll and your medical, dental and vision coverage options.
2.
The cost of Medicare Part A is typically free
You are eligible for premium-free Part A if you are age 65 or older and you or your spouse worked and paid Medicare taxes for at least 10 years. If you don't qualify for premium-free Part A, you can purchase it.
3.
Whether or not you enroll in Medicare Part B depends on the size of your employer
Medicare Part B covers doctors' services, outpatient care, preventive services, home health care and other medical services. With Medicare Part B, you will pay a monthly premium.
If your company has 20 or more employees, you can delay enrolling in Part B without worrying about a late enrollment penalty or a gap in coverage. Your employer’s coverage will be your primary insurance. When you leave your job, you’ll need to sign up for Part B within eight months or you might have to wait until the next General Enrollment Period.
If your company has fewer than 20 employees, your employer will likely require you to enroll in Medicare Part B when you turn 65. If so, Medicare will become your primary coverage and your employer’s insurance plan would become secondary. If you don't sign up for Part B as soon as you're eligible, you may have to pay a penalty, and you could experience a delay in coverage.
4.
You can no longer contribute to a health savings account (HSA) once you enroll in Medicare
Once you enroll in Medicare, you can no longer contribute toward your HSA. However, you may still use your HSA to pay for qualifying expenses.
If you have employer-sponsored coverage with an HSA, you may want to delay signing up for Medicare. Contact your human resources department or tax advisor for more details.
5.
You may need Medicare Part D (prescription drug coverage)
Prescription drugs are not covered under Medicare Part A or B. Whether or not you need to sign up for a Part D plan right away depends on if your employer has a prescription drug plan that’s considered “creditable.”
Creditable coverage means your employer plan is expected to pay, on average, as much as the standard Medicare prescription drug plan. If you are eligible for Medicare, your employer will let you know each year if the drug coverage they offer is creditable.
- If it’s creditable, you don’t have to sign up for Part D at 65 years old. When your employer coverage ends, you'll have a two-month Special Enrollment Period to sign up for a Part D plan without incurring a late enrollment penalty.
- If it's not creditable, you will need to enroll in Part D at 65 during your Initial Enrollment Period.
6.
Your options when you retire
If you lose your employer coverage after retirement, you can still sign up for Medicare. You’ll qualify for a Special Enrollment Period, which allows you to switch plans or sign up for Medicare outside of the General Enrollment Period without penalty. Your Special Enrollment Period starts after your employment ends or your employer coverage ends — whichever comes first. Then:
- You’ll have eight months to sign up for Part A (if you haven’t yet) and/or Part B.
- You’ll have two months to enroll in Parts C or D.
- You’ll have six months to choose a Medicare Supplement plan without needing to answer any health questions.
Making your best Medicare decisions
Now that you know how employment impacts Medicare enrollment, you can venture ahead on your Medicare journey with confidence. But if you still have questions, our free Medicare Supplement Coverage Guide can help.
Disclosures
All Wellmark Medicare Supplement plans are subject to restrictions and may be discontinued. For costs and complete coverage details, call your local agent or Wellmark.
This is a solicitation of insurance. Enrollment and coverage in a MedicareBlueSM Supplement insurance plan is with Wellmark Blue Cross and Blue Shield and is not connected with or endorsed by the U.S. government or the federal Medicare program.